What Makes You Eligible for PMI Removal Through Appraisal in New Jersey?
Eligibility for Private Mortgage Insurance (PMI) removal in New Jersey depends on reaching 20% equity in your home, either through mortgage paydown or market appreciation. A certified appraisal provides the objective evidence lenders require to verify this equity. New Jersey Real Estate Appraisal Group (NJREAG) helps homeowners document their equity accurately to stop unnecessary monthly insurance costs.
The 20% Equity Threshold and Lender Rules
PMI is required when you purchase a home with less than 20% down. Lenders mandate this insurance to protect themselves against default. You become eligible to cancel PMI when your loan balance drops to 80% or less of the home's original purchase price. This is known as the 80% loan-to-value (LTV) ratio. Reaching this threshold is the primary trigger for removal.
However, the rules for automatic cancellation differ from those for manual requests. Under federal regulations, lenders must automatically terminate PMI when your principal balance reaches 78% of the original value. This happens without you needing to do anything. If you want to remove PMI earlier, at the 80% mark, you must request it manually. This is where an appraisal becomes essential. Your lender will not accept a guess or an online estimate. They need a formal, certified appraisal to confirm your current equity.
Market Appreciation and Home Value Increases
Market appreciation is a powerful tool for PMI removal. It allows you to stop paying for insurance sooner than you might have expected. However, you must prove this appreciation with a certified appraisal. Online tools like Zestimate provide estimates, but they are not accepted by lenders for official PMI cancellation. A professional appraisal provides the documented, defensible value that your mortgage servicer requires. This ensures that your equity is recognized and your monthly payments are reduced.
Home Improvements and Value-Adding Upgrades
Significant home improvements can also boost your equity and qualify you for PMI removal. Upgrades that increase your home's market value, such as a kitchen remodel, bathroom renovation, or adding square footage, can push your equity past the 20% threshold. These improvements must be substantial and verifiable. Cosmetic changes alone may not be enough to justify a higher appraisal value. The appraiser will assess the impact of your upgrades on the overall market value of the property.
When you make major improvements, it is wise to get an appraisal to see if your equity has increased enough to remove PMI. This is especially true if you have been paying down your loan slowly. The appraisal will document the new value of your home, taking your improvements into account. This provides the evidence your lender needs to approve the cancellation. By combining loan paydown with strategic improvements, you can accelerate your path to PMI removal and save money over time.
The Appraisal Process for PMI Removal
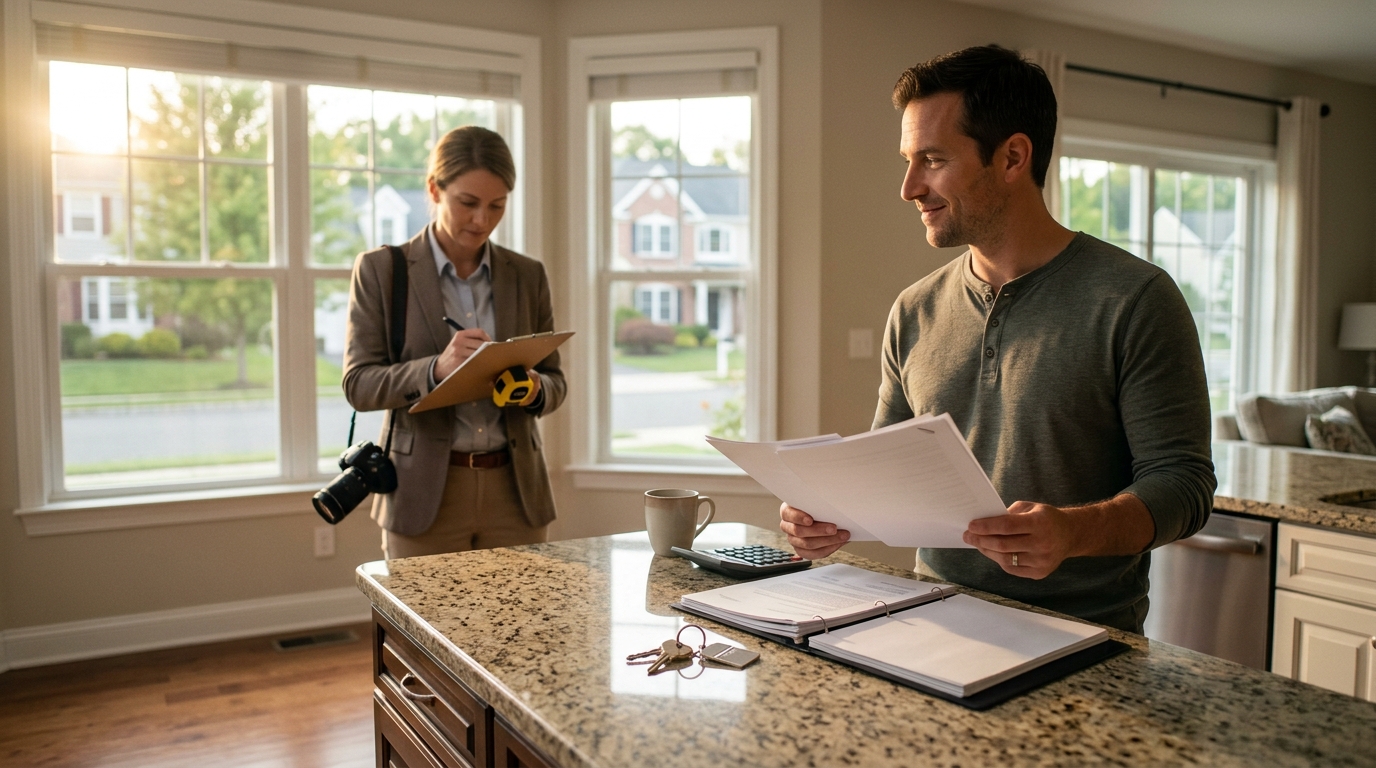
Requesting an appraisal for PMI removal is a straightforward process. First, you contact a certified appraiser, such as NJREAG, to schedule an inspection. The appraiser will visit your home to inspect both the interior and exterior. They will measure the property, assess its condition, and note any upgrades. This inspection is crucial because it ensures the appraisal reflects the current state of your home.
After the inspection, the appraiser analyzes recent comparable sales in your neighborhood. They adjust these sales for differences in size, condition, and location to determine your home's market value. The final report includes a detailed analysis of your equity. You then submit this report to your mortgage servicer. Once they verify the equity, they will cancel your PMI. The entire process typically takes a few weeks, but the savings can last for years.
Common Mistakes to Avoid
Homeowners often make mistakes that delay or prevent PMI removal. One common error is assuming that an online estimate is sufficient. Lenders do not accept these for official cancellation. You must use a certified appraisal. Another mistake is waiting too long to request the appraisal. If you have reached the 20% equity mark, you should act promptly. Delaying means you continue paying for unnecessary insurance.
Additionally, some homeowners fail to provide the appraiser with relevant information about their home. Sharing details about recent improvements, permits, and upgrades can help the appraiser accurately value your property. By avoiding these mistakes and working with a professional, you can ensure a smooth and successful PMI removal process.
Key Takeaways
- PMI removal requires reaching 20% equity in your home.
- Lenders must automatically cancel PMI at 78% LTV, but you can request it at 80%.
- Market appreciation and home improvements can accelerate your eligibility.
- A certified appraisal is required; online estimates are not accepted by lenders.
- The appraisal process involves an inspection and comparable sales analysis.
- Submitting the appraisal to your mortgage servicer triggers the cancellation.
- Acting promptly after reaching the equity threshold saves you money.
Frequently Asked Questions
How much does a PMI removal appraisal cost in New Jersey?
Most PMI removal appraisals in New Jersey range from $495 to $750, depending on the property size and location.
How long does the PMI removal process take?
The appraisal process typically takes 2 to 5 business days after the inspection. The lender may take additional time to process the cancellation.
Can I use a Zestimate to remove PMI?
No, lenders do not accept online estimates like Zestimate for official PMI cancellation. You must use a certified appraisal.
What if my home value has decreased?
If your home value has decreased, you may not have enough equity to remove PMI. You will need to continue paying down your loan until you reach the 20% threshold.
Do I need to be in good standing with my loan?
Yes, you must be current on your mortgage payments to be eligible for PMI removal. If you are behind on payments, you will not qualify.
Can I remove PMI if I have an FHA loan?
FHA loans have different rules. PMI on FHA loans is called MIP and has different cancellation requirements. Consult your lender for specific details.
Who should I contact to get a PMI removal appraisal?
You can contact NJREAG for a certified PMI removal appraisal in New Jersey.